Crypto Tax for Journalists: 2026 US Implications & 3-Month Action Plan
Anúncios
Anúncios
Understanding the 2026 US Tax Implications for Crypto Journalists Earning in Tokens: A 3-Month Action Plan
The landscape of journalism is rapidly evolving, with an increasing number of professionals, especially those covering the burgeoning blockchain and cryptocurrency sectors, receiving compensation in digital tokens. While this offers exciting new avenues for remuneration and aligns with the decentralized ethos of their subject matter, it also introduces a complex web of tax implications. As we look towards 2026, the United States tax authorities, primarily the IRS, are continually refining their stance on digital assets, making it imperative for crypto tax journalists to proactively understand and prepare for their tax obligations. This comprehensive guide provides a three-month action plan to navigate the intricate world of US crypto taxation for journalists earning in tokens, ensuring compliance and minimizing potential pitfalls.
The IRS considers cryptocurrency as property for tax purposes, not currency. This fundamental classification has far-reaching consequences, treating every transaction involving crypto as a taxable event. For journalists, this means that receiving tokens for services rendered, holding them, or later selling/exchanging them, can all trigger tax liabilities. The 2026 tax year is particularly salient as regulatory clarity is expected to improve, but so too is enforcement. Therefore, understanding the nuances of how income is reported, capital gains are calculated, and how to maintain impeccable records is not just good practice – it’s essential for any crypto tax journalists.
Month 1: Foundation and Initial Assessment for Crypto Tax Journalists
The first month of your action plan should focus on establishing a solid foundation of understanding and gathering all necessary information. This involves a deep dive into how your token earnings are classified and what initial steps you need to take.
Understanding Income Classification
For crypto tax journalists, the primary challenge often lies in correctly classifying income received in tokens. When you receive cryptocurrency as payment for your journalistic services, the fair market value (FMV) of that cryptocurrency, in US dollars, at the time of receipt, is considered taxable ordinary income. This is no different than receiving payment in fiat currency, but the volatility of crypto adds a layer of complexity.
- When is income recognized? The moment you gain control over the tokens, their USD value at that exact time is your taxable income. This means if you are paid 1 ETH when ETH is $2,000, you have $2,000 of ordinary income. If ETH drops to $1,500 the next day, your income remains $2,000.
- Self-Employment Tax: Most journalists operate as independent contractors. Therefore, income earned in crypto is subject to self-employment taxes (Social Security and Medicare), in addition to regular income tax. This means you’ll need to pay both the employer and employee portions of these taxes.
- Form 1099-NEC: If you are paid more than $600 by a single entity (e.g., a publication, a DAO) in crypto, they might be required to issue you a Form 1099-NEC. However, many decentralized projects or international entities may not. It is your responsibility, as a crypto tax journalist, to track and report all income regardless of whether you receive a 1099.
Gathering Transaction History
This is perhaps the most critical initial step. You need a comprehensive record of every single crypto transaction you’ve made, especially those involving income. This includes:
- Dates of receipt: The exact date and time you received tokens.
- Amount of tokens received: The quantity of each specific token.
- Fair Market Value (FMV) at receipt: The US dollar value of those tokens at the precise moment of receipt. This can be challenging due to price fluctuations, but reliable data sources (e.g., CoinMarketCap, CoinGecko, or exchange APIs) are essential.
- Sender/Payer information: Who paid you and for what service.
- Wallet addresses: Both your receiving address and, if possible, the sender’s.
- Purpose of transaction: Clearly note if it was payment for an article, a bonus, a grant, etc.
Start by exporting transaction histories from all exchanges, wallets, and platforms you use. This could include centralized exchanges (Coinbase, Binance), decentralized exchanges (Uniswap, SushiSwap), and even direct wallet-to-wallet transfers. For on-chain transactions, blockchain explorers can be invaluable.
Understanding Cost Basis
The FMV of the tokens at the time you receive them becomes your cost basis. This is crucial for calculating capital gains or losses later. If you receive 1 ETH valued at $2,000, your cost basis for that 1 ETH is $2,000. When you later sell or exchange it, this cost basis will be used to determine your gain or loss.
Initial Software/Tool Research
Manually tracking every crypto transaction can quickly become overwhelming. During Month 1, research and select a reputable crypto tax software (e.g., CoinTracker, Koinly, TaxBit, CryptoTaxCalculator). These tools can integrate with exchanges and wallets, import your transaction data, and help calculate your tax liabilities. Ensure the software supports the specific tokens and platforms you use and is compliant with US tax law. Many offer free tiers for limited transactions, allowing you to test their functionality.
Month 2: Deep Dive into Capital Gains, Losses, and Record-Keeping
With your foundational understanding and initial data gathering complete, Month 2 focuses on the more complex aspects of capital gains and losses, and establishing robust record-keeping practices that are vital for any crypto tax journalist.
Capital Gains and Losses for Crypto Tax Journalists
Once you’ve received tokens as income, they are treated as property. Any subsequent disposition of these tokens (selling, exchanging for other crypto, using to buy goods/services) will trigger a capital gain or loss. This is a separate taxable event from the initial income recognition.
- Selling Crypto for Fiat: If you sell your 1 ETH (which had a cost basis of $2,000) for $2,500, you have a capital gain of $500. If you sell it for $1,800, you have a capital loss of $200.
- Exchanging Crypto for Other Crypto: This is a common pitfall. Exchanging ETH for BTC, for example, is a taxable event. The FMV of the ETH at the time of exchange, minus its cost basis, determines your capital gain or loss. The newly acquired BTC then takes on a new cost basis equal to the FMV of the ETH you exchanged for it.
- Using Crypto for Goods/Services: Paying for a subscription, a flight, or even a coffee with crypto is also a taxable event. The FMV of the crypto at the time of the transaction, minus its cost basis, results in a capital gain or loss.
Short-Term vs. Long-Term Capital Gains
The duration you hold the crypto before disposing of it determines whether the gain/loss is short-term or long-term:
- Short-Term Capital Gains/Losses: For crypto held for one year or less. These are taxed at your ordinary income tax rates.
- Long-Term Capital Gains/Losses: For crypto held for more than one year. These typically benefit from lower preferential tax rates, which is a significant incentive for long-term holding.
Cost Basis Methods
When you acquire the same type of token at different times and prices, and then sell only a portion, you need a method to determine which specific tokens were sold to calculate the cost basis. The IRS generally allows two methods:
- Specific Identification (SpecID): This is generally the most advantageous, as it allows you to choose which specific tokens (e.g., those with the highest cost basis to minimize gains, or lowest to harvest losses) were sold. This requires meticulous record-keeping.
- First-In, First-Out (FIFO): This assumes the first tokens you acquired are the first ones you sold. If you don’t use SpecID, FIFO is the default. This can sometimes lead to higher tax liabilities if token prices have generally risen over time.
Your chosen crypto tax software should help you manage these methods. As a crypto tax journalist, understanding which method works best for your specific transaction history is key.
Enhanced Record-Keeping Practices
This month, solidify your record-keeping. Beyond transaction histories, keep records of:
- Proof of service: Contracts, invoices, emails, or links to published articles showing the work performed for which tokens were received.
- Correspondence: Any communication with platforms or payers regarding your crypto earnings.
- Wallet ownership: Proof that you own the wallets receiving and sending crypto.
- Software reports: Save all reports generated by your crypto tax software.
- Bank statements: If you convert crypto to fiat and deposit it into your bank, keep these statements.
Organize these documents digitally, perhaps in a cloud storage service with strong security, and consider regular backups.
Month 3: Proactive Strategies, Professional Advice, and Final Preparations
The final month is about optimizing your tax situation, seeking expert guidance, and making sure all your ducks are in a row for the 2026 tax season.
Estimated Tax Payments
As an independent contractor earning in crypto, you are likely required to pay estimated taxes quarterly. The US operates on a pay-as-you-go system. If you expect to owe at least $1,000 in tax for the year, you generally must pay estimated tax. Failing to do so can result in penalties. Calculate your projected income and capital gains for 2026 and set up a plan to make these payments using Form 1040-ES. This is a critical step for any crypto tax journalist to avoid year-end surprises.
Tax-Loss Harvesting
This is a strategic move to minimize your tax liability. If you have capital gains, you can sell some of your cryptocurrencies at a loss to offset those gains. You can deduct up to $3,000 of net capital losses against ordinary income each year, and any excess can be carried forward to future years. This strategy needs careful planning and should be executed before the end of the tax year. Work with your crypto tax software or a professional to identify opportunities for tax-loss harvesting.
Considering a Dedicated Business Entity
For some crypto tax journalists, especially those with significant earnings, establishing a formal business entity (e.g., an LLC) might offer tax advantages, liability protection, and simplify financial management. Consult with a tax attorney or CPA specializing in small business and crypto to see if this makes sense for your specific situation.
Staying Informed on Regulatory Changes
The crypto regulatory landscape is dynamic. What’s true today might change by 2026. Make it a habit to stay updated on IRS guidance, Treasury Department announcements, and any new legislation concerning digital assets. Subscribe to reputable crypto tax news sources, follow tax professionals on social media, and regularly check official IRS publications. The IRS has been increasingly active in issuing guidance and pursuing non-compliant individuals, making continuous education vital for crypto tax journalists.
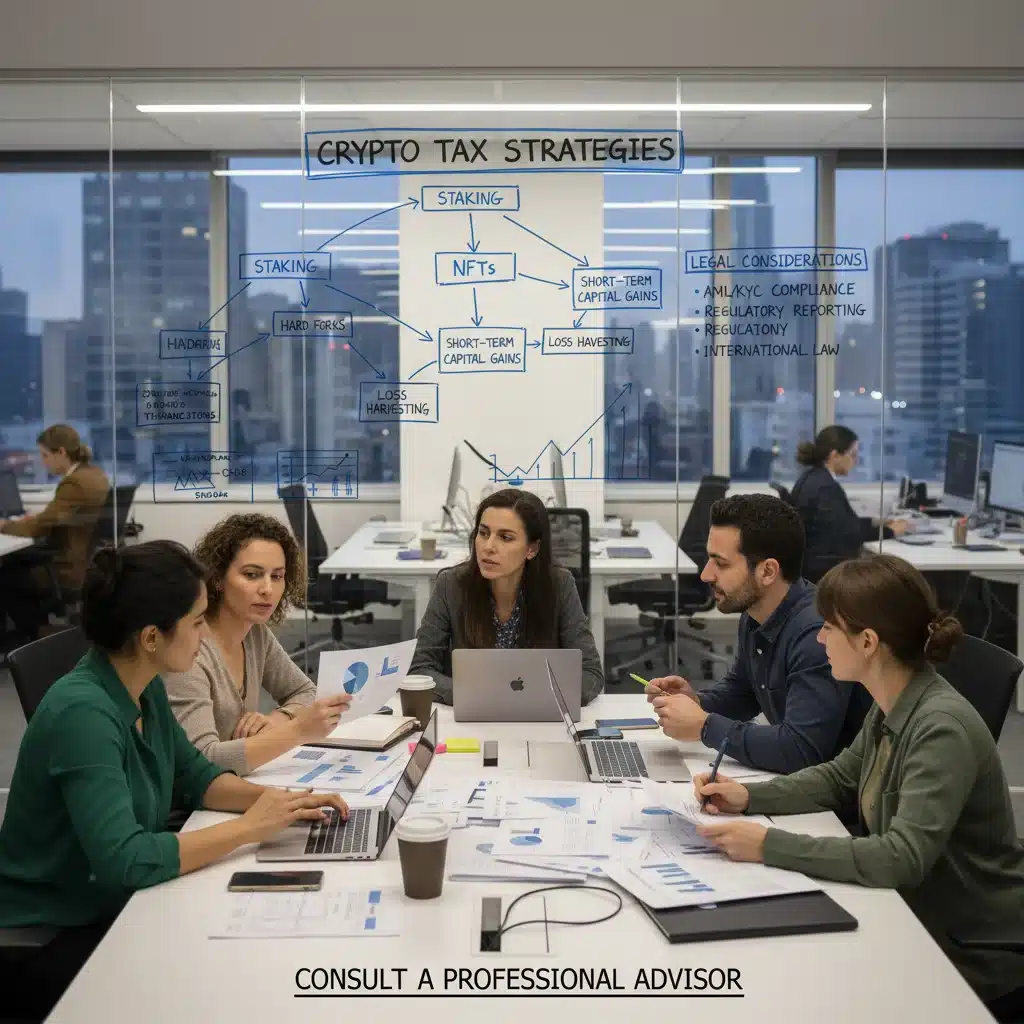
Seeking Professional Advice
While this guide provides a solid framework, it is not a substitute for professional tax advice. During Month 3, identify and consult with a tax professional who specializes in cryptocurrency. A Certified Public Accountant (CPA) or an Enrolled Agent (EA) with specific expertise in digital assets can:
- Review your records: Ensure accuracy and completeness.
- Optimize your strategies: Help you with tax-loss harvesting and other tax-efficient moves.
- Navigate complex scenarios: Address specific situations like DeFi farming, staking rewards, airdrops, NFTs, or participation in DAOs, which have their own unique tax treatments.
- Prepare your returns: Ensure your tax forms (Form 8949, Schedule D, Schedule C, etc.) are correctly filled out.
- Represent you: In case of an IRS inquiry or audit.
Look for professionals who are members of relevant industry groups or have verifiable experience in crypto taxation. A good crypto-savvy tax advisor is an invaluable asset for any crypto tax journalist.
Final Review and Contingency Planning
Before the tax year ends, conduct a thorough review of all your gathered data and calculations. Use your chosen crypto tax software to generate preliminary reports. Compare these reports against your manual records and identify any discrepancies. Have a contingency plan for unexpected events, such as a major market crash affecting your holdings or a sudden change in tax law. Ensure all your digital records are backed up securely.
Specific Considerations for Crypto Journalists Earning in Tokens
Beyond the general crypto tax rules, crypto tax journalists face a few unique situations:
- DAO Contributions and Payments: Many crypto journalists contribute to or are paid by Decentralized Autonomous Organizations (DAOs). The tax treatment of DAO rewards (e.g., governance tokens, bounties) can be nuanced. Generally, if you receive tokens for services to a DAO, it’s ordinary income. If you receive governance tokens as an airdrop without providing services, it might be income at receipt or only taxable upon disposition, depending on the specific circumstances and IRS guidance. Document all DAO interactions meticulously.
- Airdrops and Forks: If you receive free tokens via an airdrop or a hard fork, the IRS generally views these as ordinary income at their fair market value on the date and time you receive control over them. This adds to your income and creates a new cost basis for those tokens.
- Staking Rewards: If you stake your crypto and earn rewards, the IRS considers these rewards as ordinary income at their fair market value at the time you gain control over them. This is similar to earning interest.
- NFTs: If your journalistic work involves creating or selling NFTs, or you receive NFTs as payment, these also have specific tax implications. Selling an NFT typically results in a capital gain or loss. Receiving an NFT for services is ordinary income.
- International Payments: Many crypto projects are international. While US citizens and residents are taxed on their worldwide income, receiving crypto from foreign entities might add complexity to reporting, especially if those entities do not provide traditional tax forms.
Conclusion: Empowering Crypto Tax Journalists for 2026 and Beyond
The world of cryptocurrency taxation is undeniably complex, but with a structured approach, crypto tax journalists can confidently navigate their obligations. This three-month action plan – focusing on foundational understanding, diligent record-keeping, and proactive strategic planning – is designed to empower you to prepare effectively for the 2026 tax year.
Remember, the key to successful crypto tax compliance lies in meticulous documentation from day one. Every token received, every exchange made, every dollar value at the time of transaction – these details are your shield against potential IRS scrutiny. Leverage technology through crypto tax software, but always complement it with the human expertise of a qualified tax professional specializing in digital assets.
By taking these steps, you not only ensure compliance with current and anticipated tax laws but also gain a clearer financial picture of your earnings in the exciting, volatile, and ever-evolving crypto space. Don’t wait until the last minute; start your 2026 crypto tax preparation today and secure your financial future as a pioneering crypto tax journalist.